Sorry, no results.
Please try another keyword
Practice Management Integration
Streamline administrative tasks and optimise workflows
Access our support guides for comprehensive self-help assistance
Discover an ecosystem of trusted partners designed to support your matters
Allows suppliers to connect their products and services with the InfoTrack Ecosystem
Find out the latest industry updates
Take on compliance with confidence
Take your professional development to the next level
Cyber Security Awareness Training
Build your cyber resilience
Discover leading edge property insights
Access InfoTrack directly inside Claude Cowork
AUSTRAC expected between 85,000 and 90,000 new reporting entities to enrol under Tranche 2 of the AML/CTF reforms. As at the most recent count, only around 40,000 had done so. That gap says less about resistance to the reforms and more about a familiar pattern. Richard Storey, partner in risk consulting at Grant Thornton, points to the same slow start seen when banks, superannuation funds, and insurers came under the regime in Tranche 1, a delay that eventually required direct intervention from AUSTRAC before adoption picked up. For legal practitioners, conveyancers, accountants and real estate agents now navigating Tranche 2, the early lessons from those who have already implemented the reforms offer a clearer path than the legislation alone.
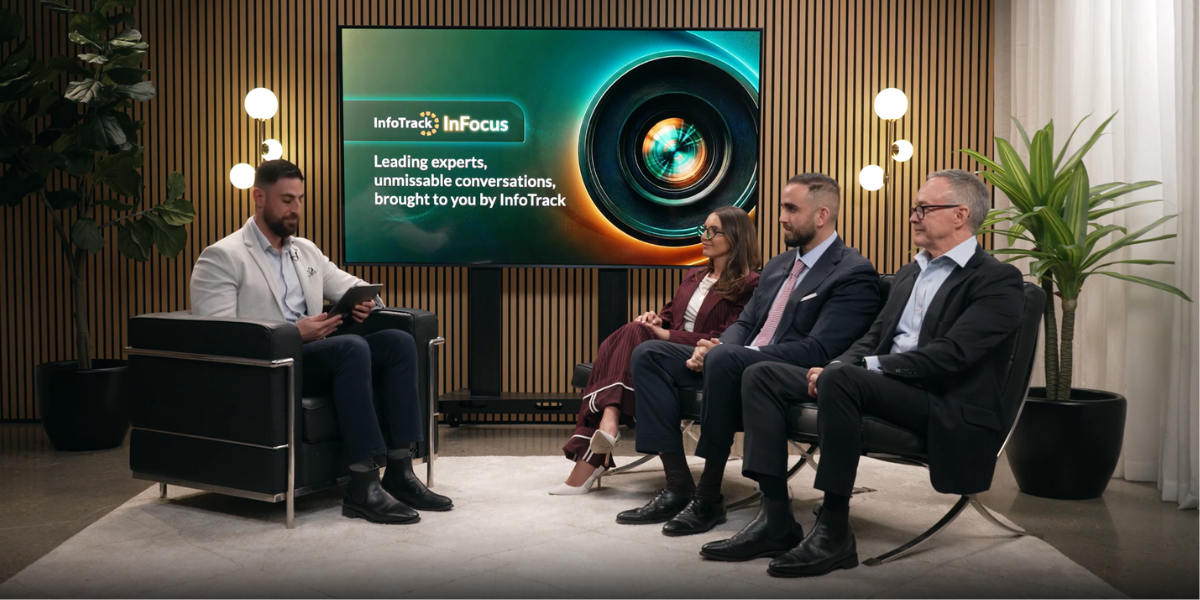
Storey, speaking alongside practitioners Renee Roumanos and Joseph Khoury Gebrail on InfoTrack’s InFocus vodcast, identifies over-collection as one of the most common errors firms make in the early months of compliance. The AML/CTF Act is deliberately principles-based rather than prescriptive, requiring a risk-based approach rather than a fixed checklist. That flexibility is valuable, but it also means practitioners can default to asking for more information than a transaction actually warrants.
Source of funds and source of wealth checks are a clear example. Storey notes that these deeper checks are only required in genuinely high-risk situations, such as when a client is a politically exposed person or has triggered a watchlist screening result. A young client purchasing a property without finance, for instance, may simply be receiving support from family, a scenario that a short conversation can usually clarify without escalating into a formal financial interrogation. Khoury Gebrail summarises the practical approach his firm has adopted: “do not over-cook it”.
A second recurring misconception concerns Reliance, the ability for one reporting entity to rely on another’s know your client and due diligence work rather than duplicating it. Storey explains that Reliance is not as simple as requesting a colleague’s file. A firm relying on another party’s due diligence still needs to understand whether that party operates a compliant AML/CTF program and whether their processes align with its own risk expectations.
Used correctly, Reliance agreements reduce the burden on clients who might otherwise be asked to complete verification of identity and know your client checks multiple times across a single transaction, once by their financier, again by a real estate agent, and again by their conveyancer or lawyer. Roumanos describes Reliance agreements with trusted real estate agents in her local area as a way of protecting clients from paying for duplicated checks, a practical benefit that goes directly to client experience as well as compliance efficiency.
Client due diligence does not end once a matter begins. Roumanos points to a common scenario in property transactions, where a client’s financing arrangement changes midway through a deal, for example when a bank declines finance late in the process and a private or family loan appears in its place. That kind of change in instructions is precisely the trigger that should prompt a fresh look at the transaction, not because it necessarily indicates wrongdoing, but because circumstances have materially shifted.
Storey adds a further dimension particular to property law, the gap between initial due diligence and settlement. A transaction that takes six weeks or more to settle creates a window in which a client’s circumstances, and their risk profile, can change substantially. Ongoing monitoring tools built into a compliance program are designed to catch exactly this kind of shift, rather than relying on a single point-in-time check at the start of the matter.
For practitioners concerned about liability if a client is later found to have acted unlawfully, Storey offers a clear standard. A firm that has taken reasonable steps and acted on information that was reasonably available to it at the time, is unlikely to face regulatory consequences for failing to detect what a client concealed. The threshold is not omniscience; it is diligence proportionate to the risk presented at the time.
That said, several of the practitioners note a genuine tension in the reforms, the requirement to report suspicious activity sits uneasily alongside a lawyer’s fiduciary duty to act in a client’s best interest. Khoury Gebrail describes this as one of the more difficult adjustments for practitioners used to complete client confidentiality. It is a tension the reforms create by design, and one that is likely to remain a point of professional discomfort even as the process itself becomes routine.
The clearest advice across the panel is consistent. Appoint a compliance officer early, invest in established systems rather than building ad hoc processes, and lean on the wider legal community for support rather than navigating the reforms alone. Storey suggests that as identity verification becomes as familiar in legal transactions as it already is in banking, where deposits and withdrawals over nine thousand dollars routinely prompt questions, practitioners and clients alike are likely to find the process far less onerous than it currently feels.
For firms still finding their footing, the panel’s shared message is straightforward, ask for help. Whether that is a colleague, a technology provider, or AUSTRAC directly, every practitioner interviewed described a profession willing to support firms working through the same challenges in real time.
To hear all the insights from this conversation, watch the on demand session here.